
Deck Feedback Requests: How to Ask and What to Do Next
How to write deck feedback requests that get answers: who to ask, the exact questions, how to sort the replies, and how to handle a deck that gets forwarded.
November 6, 2026 · 13 min read

A good deck feedback request gives the reviewer a small, specific job with a clear time limit. It does not ask for a favor. Name the slides you want read, the one question you need answered, and how long it will take. Send it to a person who has seen many decks and has no reason to be polite. Then treat every “I got lost here” as a defect in the deck.
This guide covers who to ask, what to write, which questions find real problems, how to sort the replies, and what to plan for when your deck gets forwarded to someone you never wrote to.
BabyLoveRaiseSee Where Readers Lose the ThreadBabyLoveRaise tracks investor engagement slide by slide, helping you spot where readers lose interest and focus your deck revisions.Explore deck trackingTL;DR
- Ask for a bounded job: “read the slide titles for 60 seconds and tell me the story back,” then “mark where you got confused.”
- Pick reviewers who read many decks: founders who raised recently, early-stage investors who are not on your target list, accelerator coaches.
- Send three or four pointed questions, not “what do you think?”
- If several readers stumble on the same slide, fix that slide first. Treat one person’s taste as a preference, not a verdict.
- Assume the deck will travel. Write a one-liner a stranger can repeat, and use a link you control.
Table of Contents
- Write the ask as a small job
- Who to ask, and when
- Questions that expose what is unclear
- Sort the feedback: what to fix and what to ignore
- Where your deck goes after you send it
- See where feedback readers stop
- FAQ
- Sources
Write the ask as a small job
The weakest request in fundraising is “Could you take a look at my deck and tell me what you think?” It is open-ended and has no deadline, so it goes to the bottom of the inbox. Busy people who are qualified to judge a deck are the same people with no spare time. Talkpitch notes that you get better results by asking something specific, such as where you lost the reader, and by setting a clear, bounded time commitment.
A structure that works comes from Chicago Brandstarters: state the specific problem, the specific action you want, and why it matters to a decision in front of you. Their approach also recommends choosing a warm, direct channel over a vague public post, saying how long it will take, and leaving room for a smaller yes.
Here is that structure applied to a pre-seed deck:
Hi Dana, I’m opening my seed round in three weeks and I’m too close to the story. Could you read slides 3 through 8 and tell me whether the customer problem and our wedge are clear? Ten minutes, and a few blunt lines by email is perfect. If that’s too much, even “slide 5 lost me” helps.
That message does four things. It gives a reason the person should care, narrows the scope to a handful of slides, names the format, and offers a smaller yes. The reviewer can answer in one line, and that makes a reply far more likely.
The 60-second test
One ask is worth using with almost any reviewer. StartWise suggests a two-pass read. First the reviewer skims only the slide titles for about 60 seconds and tells the story back to you. Then they read the whole deck and mark where they got confused or stopped believing you.
The first pass tests whether your titles carry the argument. If someone cannot retell your story from the headlines, investors skimming on a phone will not be able to either. The second pass finds the specific slides where the argument breaks.
Who to ask, and when
Ask before the deck goes to any investor on your target list. After that, a rewrite costs you a first impression. Aim for people who read many decks and have no reason to flatter you:
- Founders who raised recently. They remember which objections came up and what finally worked. The Fundraising Lore points out that VC-backed founders tend to have a good sense of the objections investors will raise, and suggests asking for about 30 minutes of their time.
- Early-stage investors who are not targets for this round. They know how decks are judged, and nothing you say changes their decision.
- Accelerator or incubator coaches and mentors who have raised capital. UpMetrics lists pitch consultants, mentors, trusted early-stage investors, founders who have raised, and accelerator coaches as the people who know how pitches are judged. It also suggests choosing three of its questions rather than sending everything at once.
- Friends, family and customers. Useful for one thing: can someone outside the industry follow the problem and the product? They are rarely good judges of whether an investor will bite.
StartupFundraising.com recommends sending the deck to three trusted founders who have successfully raised and asking three questions by email. Three is a good number. It is enough to see a pattern and small enough that you will actually read and weigh every reply.
A practical order: start with someone friendly outside the industry to check basic clarity, then a founder who raised recently, then an investor or coach for a judgment call. Each round should be one revision apart, so the next reviewer is not repeating the last reviewer’s notes.
Questions that expose what is unclear
Specific questions get specific answers. These come from the sources above and from common practice:
- “What is the single most confusing slide?” From StartupFundraising.com. It forces one answer instead of a vague tour.
- “What is one thing you would cut, no questions asked?” Same source. Decks usually have too much, and a reviewer’s first cut is revealing.
- “On a scale of 1 to 10, how likely would you be to take a meeting based on this deck alone?” Same source. Follow with “what would move it up one point?”
- “What is the one part of this pitch that would make a seed investor say no?” Talkpitch recommends this and “Where did I lose you?” over a general request to watch and comment.
- “What would you ask me first?” Their first question is the slide you left unanswered.
- “Can you tell me in one sentence what we do, for whom, and why it will work?” If the sentence is wrong, the deck is wrong.
For a reviewer with more time, ask them to write out any outstanding questions they still have about the business. LivePlan advises this, and says to look for consistent gaps and find ways to add them in. Questions a reader is left holding are a to-do list for your next draft.
Also know what type of feedback you want before you approach anyone, as LivePlan says. Clarity of story, strength of traction, and design polish are three different requests, and one reviewer is rarely best at all three.
A short checklist for the reviewer
If you want to hand over a checklist, keep it to what matters to an investor reading cold:
- Is the problem stated before the product?
- Is the evidence traction rather than projection?
- Is the ask explicit, with what the money buys?
- Is the market size built from the bottom up?
- Does each slide carry one idea?
Five items are plenty. A twenty-point rubric makes the reviewer feel graded and gets you shorter answers.
Sort the feedback: what to fix and what to ignore
Now you have three to five replies, some contradictory. Sorting them is the real work.
“I did not understand this” is always valid. A reader cannot be wrong about their own experience. If three of five readers stumble on the same slide, that slide moves to the top of your list. “I would have done it differently” is different. It may be excellent advice, but it rests on one person’s preference. This rule of thumb is also how PitchScan frames it.
Turn comments into tasks. NUVC argues that useful feedback sounds like a task, such as “your traction slide has no specific numbers, so add monthly growth rate, total revenue to date and paying customers.” Vague notes like “make traction pop” should be turned into a task, or sent back to the reviewer with a follow-up question.
Sort into three piles. UpMetrics suggests three types: urgent fixes (anything that makes the pitch confusing or unreliable), nice-to-have suggestions (delivery or design that does not change how the pitch is understood), and contradictions. For contradictions, look at who said what and the context they bring. An investor who only backs enterprise software and a consumer-focused operator will rightly disagree.
Keep the story stable. Vestd’s Graham Charlton argues that a common fundraising mistake is treating all feedback as equal. His advice is to keep the core narrative (problem, insight, ambition) steady while changing the emphasis, instead of rewriting the whole deck for every comment. He also sorts investor feedback into traction, timing, risk and fit, and notes that only traction and timing concerns typically require changes to the pitch. Hold your line when a comment conflicts with clear customer behavior. Listen hard when several people flag the same execution or market risk.
A simple working table helps:
| Signal | What it usually means | What to do |
|---|---|---|
| 3 of 5 readers stumble on the same slide | Defect in the deck | Rewrite that slide first |
| One reader dislikes your design | Preference | Park it unless a second reader agrees |
| Two readers want opposite things | Different contexts | Check who they are, then choose |
| Everyone asks about the same missing number | Gap in evidence | Add the number or say why you lack it |
| “Not a fit for us” | Fund constraint | Do not rewrite the deck |
Once you know what to change, you still need the process around the change. Our guide to pitch deck version control covers file naming and keeping a single master, and our walkthrough of refining your startup presentation covers the editing itself. If you want mentors and investor introductions around the revision stage, equity-free accelerator mentoring is one route for founders who are ready to raise.
Where your deck goes after you send it
The person you send your deck to is rarely the only person who reads it. Plan for that in three ways.
Make the one-liner survive a retelling. Decks get forwarded to a partner who was not on the call. If your one-liner cannot be repeated by someone with no stake in it, the forward dies in the inbox. This is the point PitchScan makes. The test from the earlier checklist applies here: can a stranger say what you do after one read?
Know how reviewers forward. An angel investor profiled by Pitching Angels forwards a PDF to domain experts to confer before investing. The same investor avoids forwarding links, because colleagues who open a link get asked about investing when they were only doing a favor. The format you send shapes how the deck moves. A PDF travels freely, and a link depends on what the reader is comfortable with.

Decide what leaves your hands. If you are sending the deck for feedback rather than to a target investor, consider a trimmed version with no confidential numbers. Our piece on three-tier investor deck confidentiality lays out what to share at each stage, and the guide to private pitch deck links covers how to keep a link from wandering. For a reviewer who wants to show the deck to a colleague, a forwardable link with a clear purpose is better than an attachment you can no longer see.
One more practical habit: use date-based file names such as StartupName_PitchDeck_2026-01-15_Master, keep one master with restricted editing, and keep working copies separate from the version you send. Pitch Deck Studios recommends exactly this. When a reviewer says “on slide 6,” you need to know which version they mean.
Perspective
Most founders ask for feedback and then hear silence, and the silence is the problem. You cannot tell whether the reviewer never opened the deck, read half of it and drifted, or read everything and decided to pass. Those three look identical in your inbox, and they need three different responses.
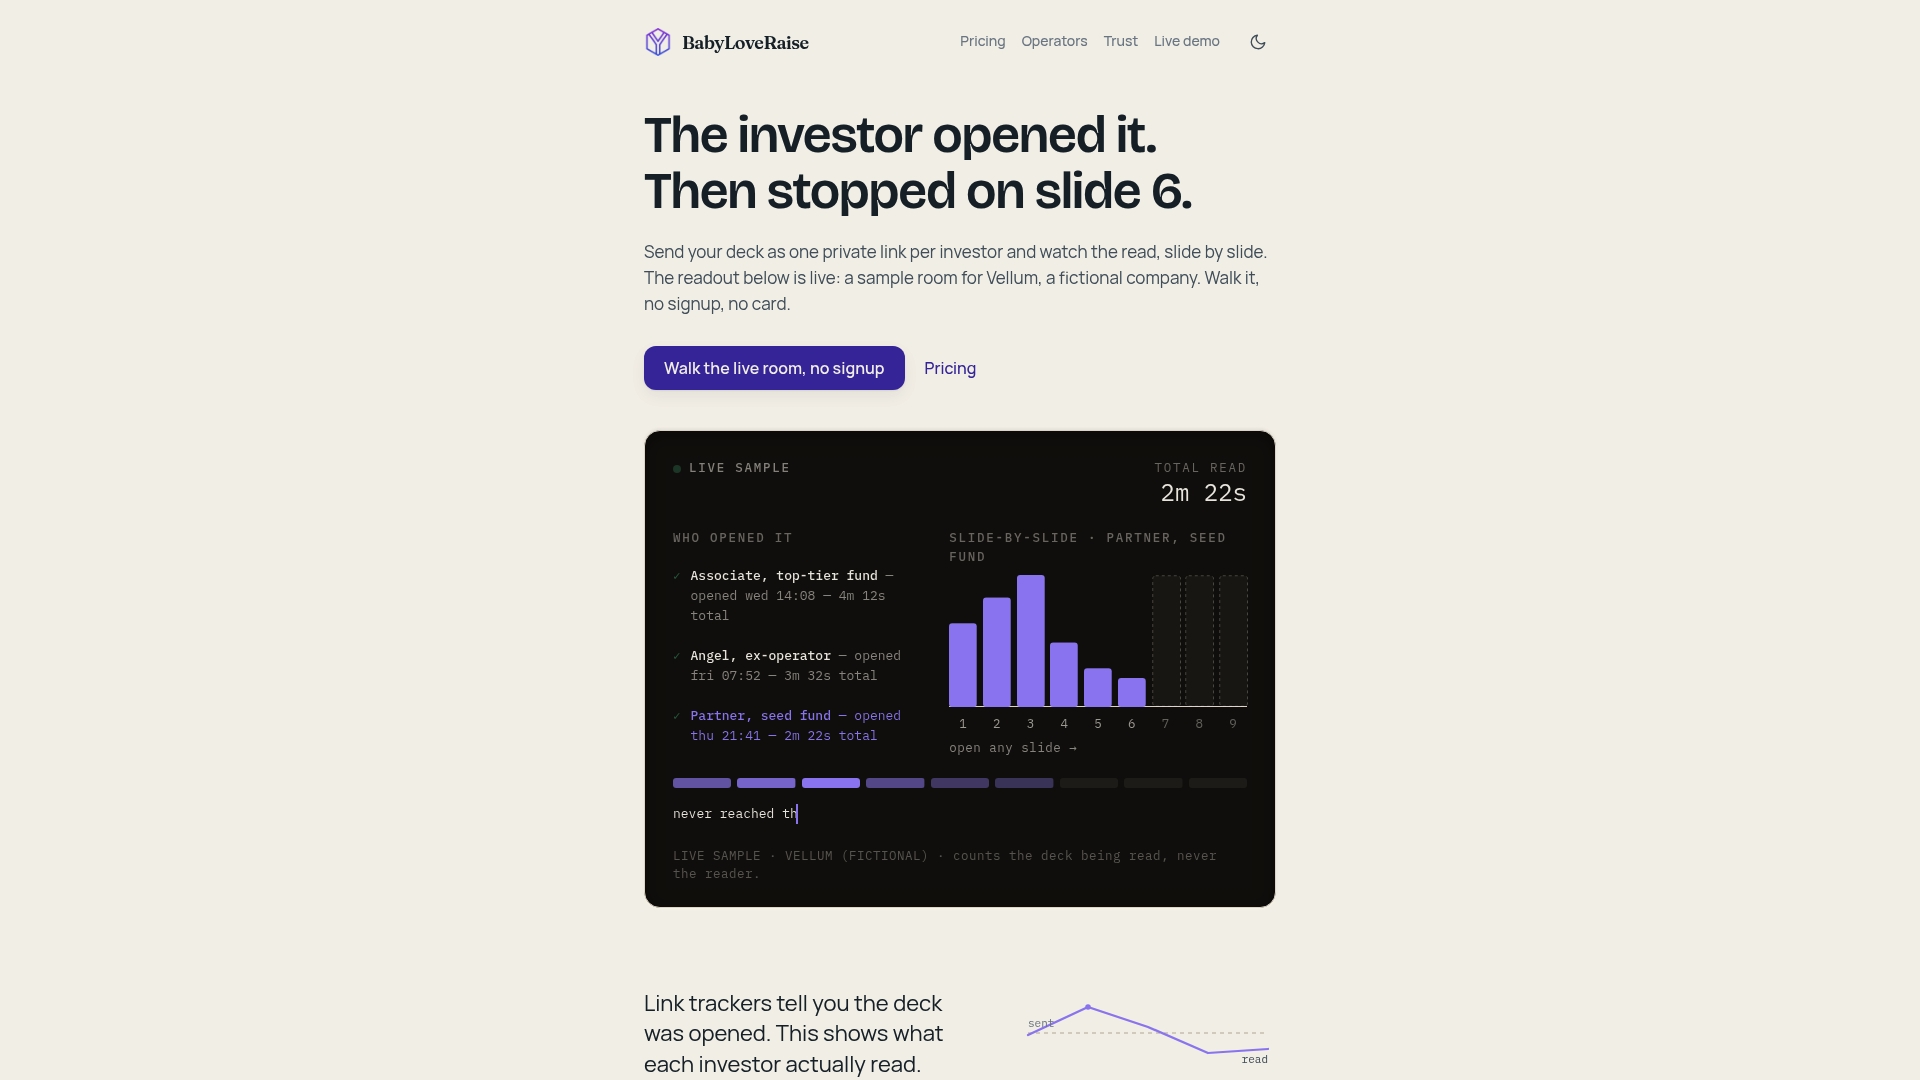
We built BabyLoveRaise around that gap. When you send one room link instead of a PDF, you are told on first read, and you can see which slides held attention and which were skimmed. A solo founder has no cofounder to watch a reader’s face. Per-slide dwell is the closest stand-in we know of. If a reviewer says the deck is “fine” but spent ten seconds on your traction slide, you now have something to ask about.
We also think tracking should report on the document and never surveil the person. Share links come in three registers (first send, forwardable and private) so that you choose how far a deck can travel before it leaves, rather than hoping. And when the raise closes, the room converts to a free permanent archive.
Feedback from people is still the main thing. The room tells you where to point your next question: not “what do you think?” but “slide 5 seems to lose people, what happened for you there?”
Paul
See where feedback readers stop
If you are about to send your deck to reviewers, send it as a room rather than an attachment. The raise room notifies you on first read and records per-slide engagement, so you can tell which reviewers finished the deck and which slides they skimmed. It costs $149 per month or $399 per quarter. A draft room and an editorial pass, a hands-on review of your deck by our team, are listed on the same page for founders who want a human read before the deck goes out. Advisory firms and fractional CFOs running several raises can look at the Operator plans, at $399 per month per seat or $3990 per year per seat.
For a deeper look at what to test once you have per-slide numbers, read our guide to running four pitch deck tests in one sitting.
FAQ
How many people should I ask for deck feedback?
Three to five is enough. Three is the minimum to see whether more than one person stumbles on the same slide, and more than five tends to produce contradictions you cannot resolve. Space the rounds so each reviewer sees a revised deck.
Should I send the deck as a PDF or a link?
A PDF is easy to forward and easy for the reviewer to share with a domain expert, but you lose sight of it once sent. A link lets you see whether it was opened and which slides were read. Whichever you choose, tell the reviewer what you want done with it, and keep the one-liner strong enough to survive a forward.
What if a reviewer gives vague feedback like “it needs more punch”?
Reply with one narrow follow-up: “Which slide, and what did you expect to see there?” Vague notes become useful when they are tied to a slide and an expectation. If the reviewer cannot answer, park the comment.
Is it a bad sign if an investor reads my deck and does not reply?
Silence has several causes: never opened, skimmed, or read and passed. Per-slide engagement data separates them, so a follow-up goes to people who actually finished the deck. Without data, a short, specific follow-up that restates your one-liner is the safest option.
Can I ask a competitor-adjacent founder for feedback?
Be selective. Ask founders in adjacent markets rather than direct rivals, and share a trimmed deck without confidential metrics until you trust the reader. Our piece on access control for investor decks covers how to limit what each reader sees.
Sources
- Talkpitch: How to Get Real Feedback on Your Pitch Before the Meeting
- Chicago Brandstarters: How to Ask for Help So People Actually Say Yes
- StartWise: Pitch Deck Review, How to Run One in Two Passes
- The Fundraising Lore: How to Network with Entrepreneurs
- UpMetrics: How to Get Feedback on Your Business Pitch
- StartupFundraising.com: How to Cut Your Pitch Deck
- LivePlan: 9 Ways to Get Feedback on Your Business Pitch
- NUVC: Why Most Pitch Deck Feedback Is Useless
- Vestd: Learning from fundraising rejection to sharpen your pitch
- PitchScan: Pitch Deck Feedback, Where to Get It and How to Use It
- Pitching Angels: Should You Send Your Pitch Deck by PDF or Link?
- Pitch Deck Studios: Pitch deck management and version control